Retirement is often imagined as a time of rest and relaxation. However, the true financial picture can be much more complicated than expected. Many retirees find themselves blindsided by costs that quietly add up, sapping their financial freedom. These costs aren’t the ones we usually think of, like medical bills or market crashes.
They’re the everyday expenses that continue to haunt us long after our working years are over. Let’s dive into the retirement costs that can quickly spiral out of control if you’re not careful.
The Hidden Expense of Keeping a Large House
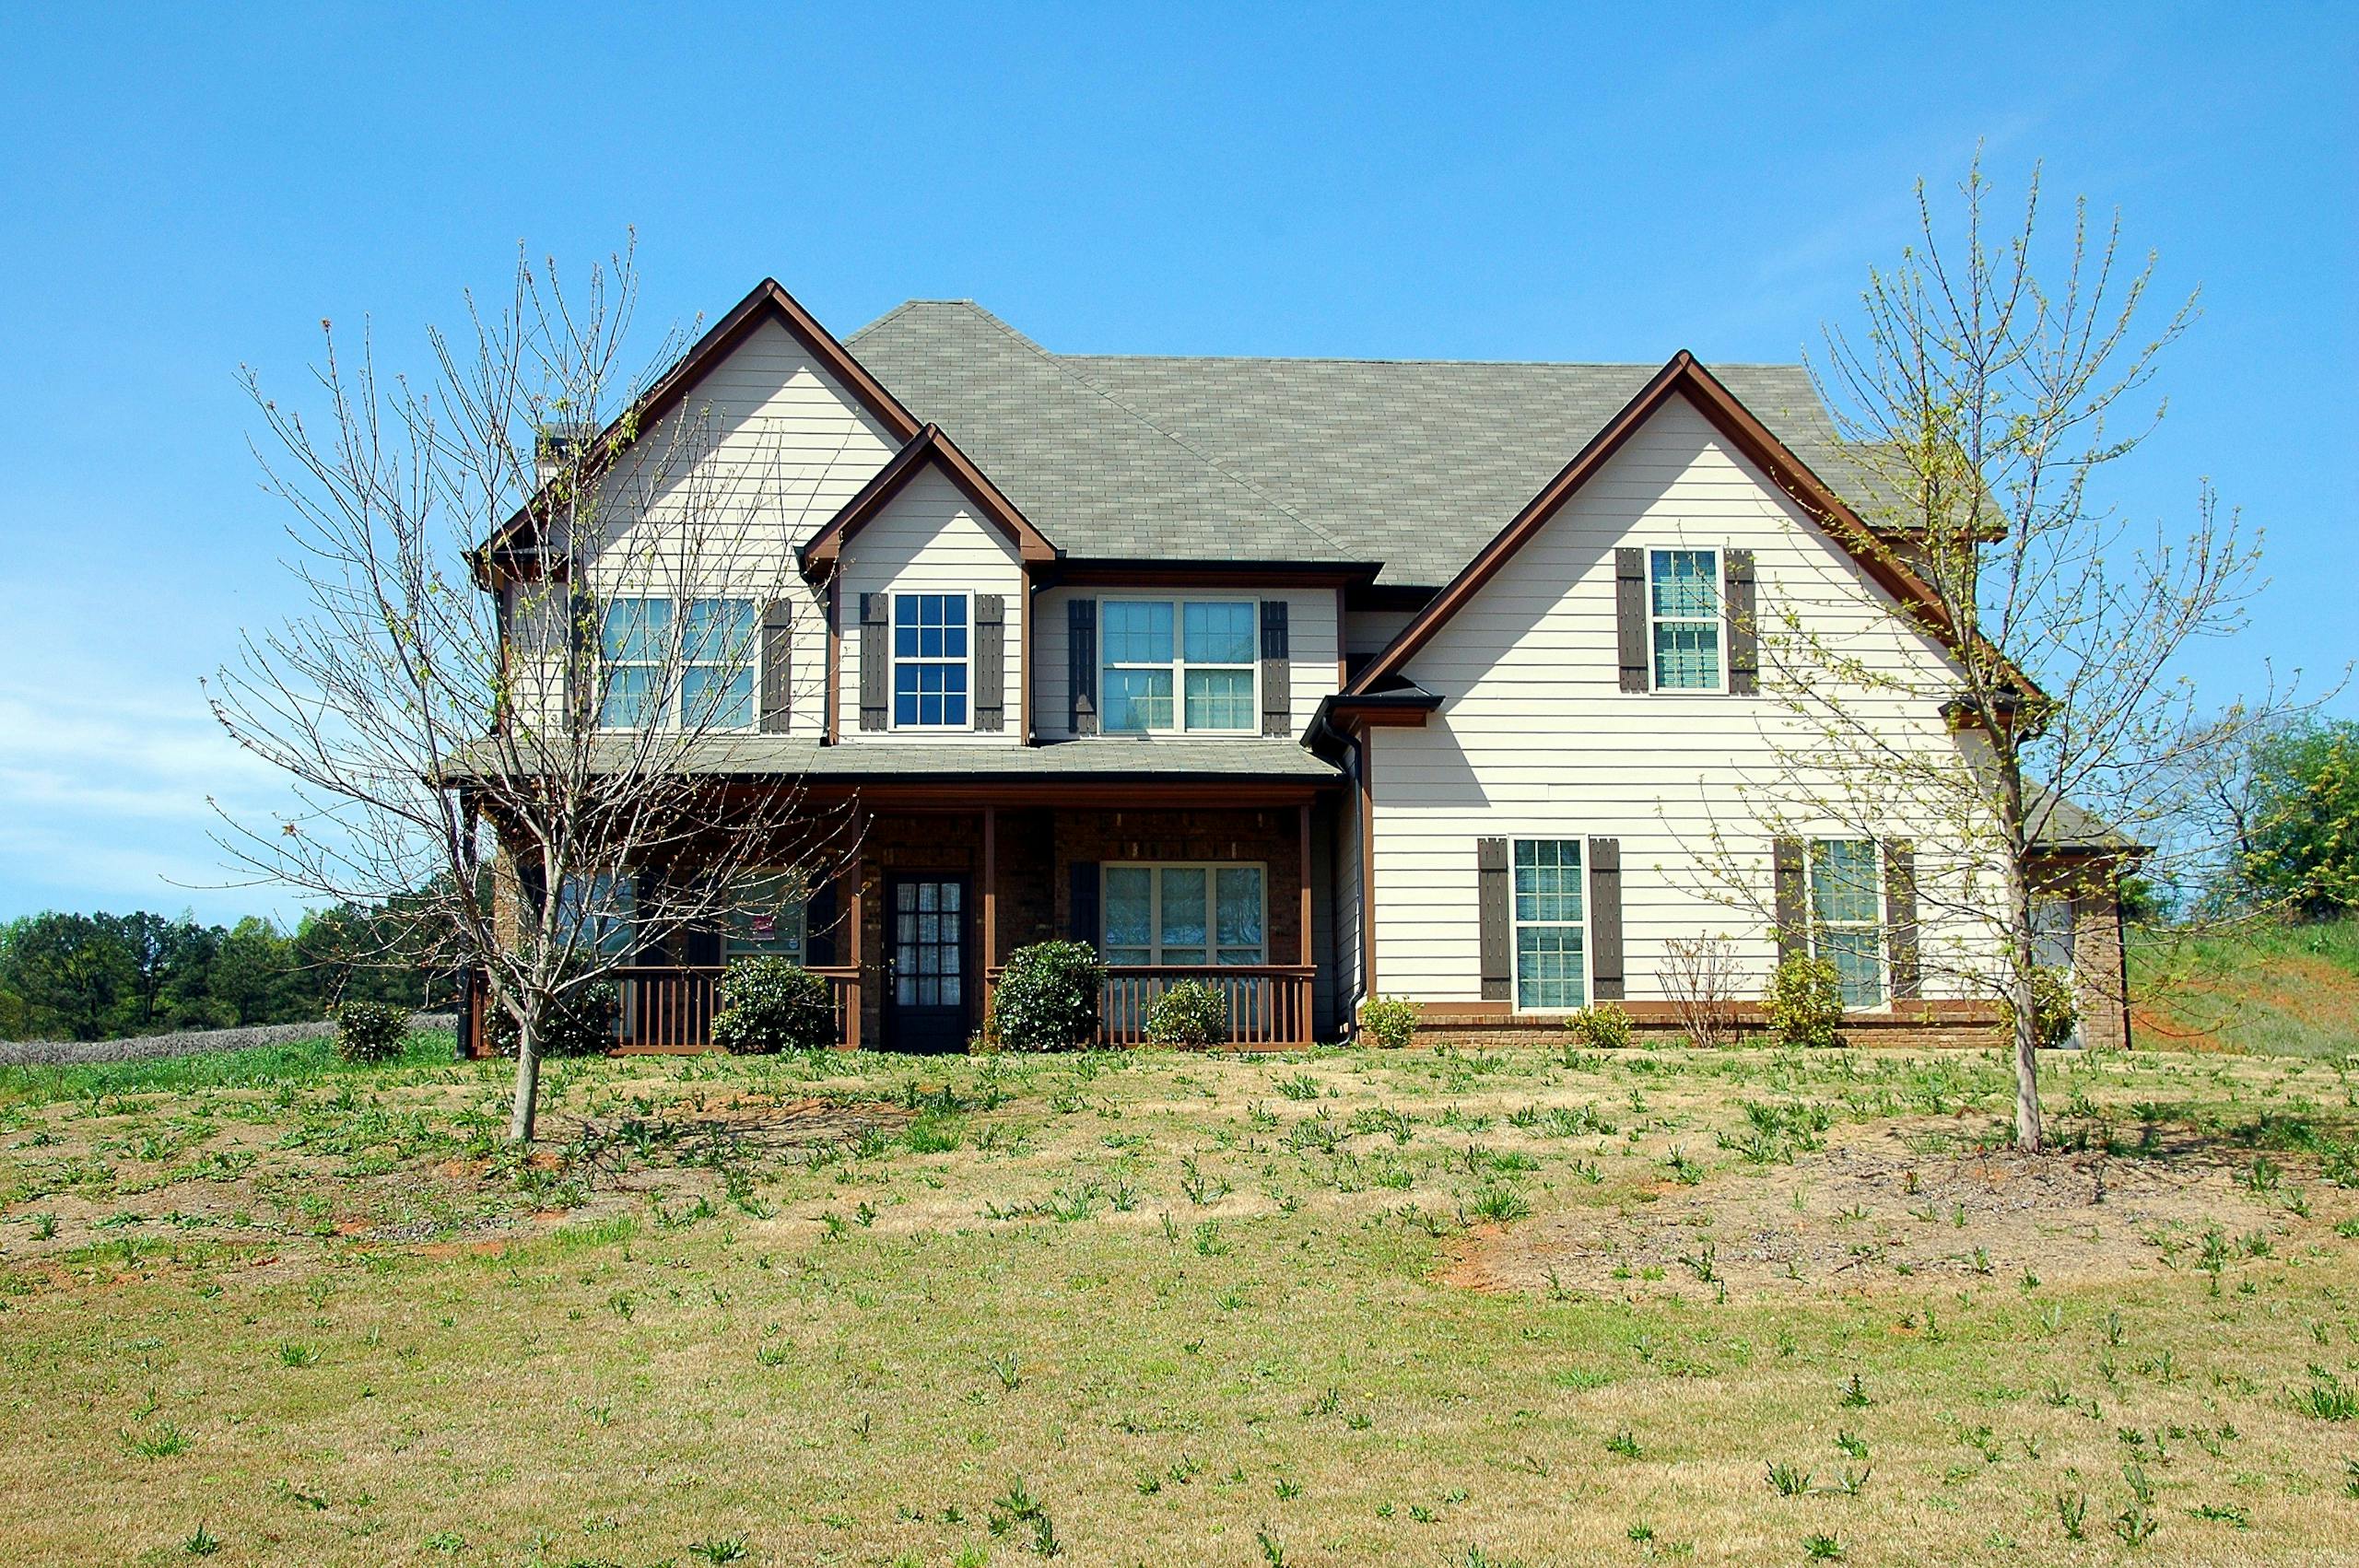
Even after the mortgage is paid off, a large home can still be one of the biggest drains on your retirement savings. The maintenance, property taxes, insurance, and utility bills can sneak up on you, eating away at your financial cushion.
While you may have loved the space during your working years, maintaining that home can become an unsustainable burden. As you age, home repairs and the cost of aging in place such as installing ramps or wider doors can escalate quickly.
If you’re not rethinking your housing situation in retirement, you could be tying up money that could be better spent on health care, travel, or simply enjoying life.
Sometimes, downsizing or relocating to a more affordable area can free up resources to improve your quality of life during retirement.
Keeping That Second Car Can Be a Drain
It’s common for retirees to hold on to a second car that was once needed for commuting. But once the daily grind of work is over, keeping that second vehicle doesn’t make much sense.
The costs of maintenance, insurance, registration, and repairs continue whether or not the car is driven regularly. This extra car may sit in the driveway, quietly wasting away valuable resources that could be better spent elsewhere.
Many retirees don’t realize just how much they’re throwing away by not re-evaluating their transportation needs. Downsizing to a single vehicle can save on insurance premiums, maintenance costs, and even parking fees. It’s an easy adjustment that can significantly impact your monthly expenses.
Overlooking Medicare Costs
Medicare can quickly become a budget buster if you miss deadlines or make the wrong choices. Delaying enrollment in Part B, for example, can result in a penalty of 10% for each year you could have had coverage but didn’t sign up.
This penalty adds up fast and becomes a permanent increase in your premiums. If you don’t stay on top of enrollment windows and plan updates, these small mistakes can lead to significant financial consequences.
Medicare mistakes are one of the most easily avoidable yet costly pitfalls in retirement. It’s crucial to understand your options, make timely decisions, and update your plan regularly to ensure it continues to meet your needs.
Subscriptions and Memberships You Forget About

Subscription services can feel harmless, but they can quietly drain your retirement savings. Whether it’s a streaming service, cloud storage, or a digital magazine subscription, these costs often go unnoticed.
Retirees, with more time on their hands, may forget about recurring charges, especially when they’re billed automatically. Before long, you’re paying for things you don’t use, and your money is tied up in services you no longer need.
It’s important to regularly audit your subscriptions. Cutting out unnecessary services or downgrading plans can have a noticeable impact on your monthly spending and help you reclaim wasted funds.
The Insurance You Don’t Need Is Still Eating Up Your Money
Old insurance policies are one of the most insidious costs retirees often overlook. From life insurance meant to protect a family in the early years of marriage to auto insurance tied to a long commute, many of these policies no longer serve your current needs.
Yet retirees continue to pay for them simply out of habit or fear of canceling. This is where psychological inertia becomes costly.
A critical part of retirement planning is reviewing every insurance policy and ensuring it still aligns with your needs. Dropping unnecessary policies can free up funds for more meaningful expenses, like health care or travel, without compromising your financial security.
Food Costs Balloon When You’re Not Paying Attention
Retirement should bring about a reduction in emergency food purchases and rushed meals. Yet many retirees continue to spend as if they’re still juggling a hectic work schedule.
Takeout, premium coffee stops, and convenience meals become easy crutches in retirement, eating away at your budget. Over time, these small expenses can add up to a surprising amount, especially when there’s no longer a clear “workday” reason to indulge.
The key to cutting food costs is awareness. Replacing takeout with home-cooked meals or limiting daily restaurant visits can help you save hundreds each month without feeling deprived. Small changes can make a big difference in keeping your budget on track.
The Financial Consequences of Ignoring Estate Planning
Estate planning is often one of the most overlooked aspects of retirement. Many people assume they’ll figure it out later, but failing to have a will or trust in place can lead to legal headaches, additional taxes, and family conflicts.
Without clear guidance on how to distribute your assets, your loved ones may face unnecessary stress and confusion. In addition, taxes on an estate without a proper plan can drain resources that should go to your heirs.
Estate planning isn’t just about transferring wealth; it’s about protecting your family and ensuring that your wishes are carried out smoothly. Take the time to establish a plan that will help avoid financial and emotional burdens for your loved ones.
The Cost of Not Taking Advantage of Senior Discounts
Retirement should be the time to take advantage of discounts and savings, especially on travel, dining, and entertainment. Yet, many retirees forget to seek out senior discounts, costing themselves more than necessary.
Programs like the National Park Senior Pass and discounted rail fares for seniors are great examples of how to reduce travel costs. Simply not asking about discounts or missing the opportunity to use them can result in overpaying for services and activities.
Take the time to ask for senior discounts and plan your travel during off-peak seasons. Retirement is meant to be a time to enjoy life, not overpay for it.
The Fraudulent Schemes That Target Retirees
Unfortunately, retirees are prime targets for fraudsters, who see them as easy marks with assets and savings worth stealing. Scammers use a variety of tactics, from fake investment schemes to impersonation scams, to steal money from unsuspecting retirees.
As the sophistication of these schemes increases, so does the financial loss. The results can be devastating, erasing years of careful planning in a single phone call or email.
It’s crucial to stay vigilant against scams in retirement. Never share personal information over the phone or online, and always verify the legitimacy of investment opportunities or requests for money.
Conclusion
Retirement isn’t just about putting away enough money; it’s about managing your expenses and staying aware of the hidden costs that can erode your savings. From the home you’ve lived in for decades to the second car you never drive, many retirement costs are quietly eating away at your financial security.
It’s easy to overlook the smaller expenses, but they can add up to big problems in the long run. By staying proactive, reevaluating your spending, and making thoughtful adjustments, you can enjoy your retirement without financial worries creeping in. It’s time to stop letting familiarity drain your resources and start living a financially secure retirement.