You work hard, you try to be responsible, and yet somehow the money never seems to go as far as it should. You are not imagining it. There are financial systems, products, and policies working quietly in the background that are designed to take more from you than you ever agreed to give. Most people never connect the dots between their financial struggles and the traps feeding on them every single month.
The frustrating part is that these traps are not obvious. They hide inside the fine print, inside the products marketed to you as helpful, and inside the systems you were told to trust. Understanding them does not require a finance degree. It just requires knowing where to look and what questions to start asking.
The Payday Loan Cycle That Never Lets You Go
Payday loans can seem like a lifeline when money is tight, but they are among the most expensive financial products ever created. Annual percentage rates on these loans can exceed 600%, meaning that a small emergency loan quickly becomes a debt that costs you far more than the original amount you borrowed. Most people who take one out end up rolling it over repeatedly, paying fees with each cycle without ever touching the principal.
The trap is that the desperation that drives someone to a payday lender is the exact condition that makes the loan impossible to escape. The interest compounds faster than most people can repay it on a regular income, and before long, the loan is consuming a significant portion of every paycheck. Credit unions, community lending programs, and negotiated payment plans with creditors are almost always a better option, even when they feel less immediately accessible.
Bank Fees That Drain You Without You Noticing
Banks make billions every year from fees that most customers never see coming. Overdraft charges, non-network ATM fees, monthly maintenance fees, minimum balance penalties, and inactivity fees all add up to a quiet but consistent drain on your account that most people never fully calculate. A single overdraft fee can wipe out an entire day’s work earnings in one transaction.
The reason these fees are so effective is that they are small enough individually to feel manageable but consistent enough collectively to cause real damage over time. Switching to a bank or credit union with transparent, minimal fee structures is one of the simplest financial moves available. Yet, most people put it off for years out of inertia. Checking your bank statements line by line every month is the first step to understanding exactly how much you are paying for the privilege of keeping your own money somewhere.
Credit Card Interest That Compounds Faster Than You Can Repay

Credit cards are among the most widely used financial tools in the world, and among the most quietly destructive when used without a complete understanding of how interest works. Carrying a balance month to month means paying interest on interest. At typical rates of 20% or higher, a modest balance can take years to repay, even with consistent monthly payments. Most people dramatically underestimate how long it takes to get out of credit card debt once it begins compounding.
The psychological trap is that credit cards feel like money you already have. Swiping feels painless in the moment, and the true cost only becomes visible weeks later on a statement that is already growing. Paying more than the minimum every single month and avoiding adding new charges while carrying a balance are the two most critical habits for escaping the credit card trap. It sounds simple because it is, but the card companies are counting on the gap between knowing and doing.
Savings Accounts That Quietly Lose Value to Inflation
Most people feel responsible for putting money in a savings account, and for good reason. Having savings is genuinely important. The trap is believing that money sitting in a standard savings account is actually growing when, in reality, it is almost certainly losing purchasing power every year. When the interest rate on your savings account is lower than the inflation rate, your money buys less next year than it does today, even though the number in your account is technically higher.
This is one of the most invisible financial traps because nothing feels wrong. Your balance looks fine, and the account feels safe. But the silent erosion of purchasing power over ten or twenty years is significant enough to meaningfully impact your long-term financial position. High-yield savings accounts, index funds, and other inflation-beating vehicles are not just for wealthy investors. They are tools available to anyone willing to understand the basic difference between storing money and growing it.
High Fee Financial Products Sold as Wealth Builders

The financial industry offers countless products that promise to grow your money while quietly extracting a significant portion of any returns through fees. Certain mutual funds, annuities, insurance-linked investment products, and managed portfolios use fee structures buried in documentation most people never read. A fund charging two percent annually in fees sounds harmless until you calculate what that costs you over thirty years of compounding returns.
The people selling these products are often genuinely enthusiastic about them, and that enthusiasm is part of what makes the trap so effective. They are also frequently operating on commission structures that reward them for selling products regardless of whether those products are the best option for the buyer. Before committing to any financial product, ask for a clear breakdown of all fees and compare the total cost with simpler, lower-cost alternatives, such as index funds. This habit could save you tens of thousands of dollars over a lifetime of investing.
Student Loan Debt That Follows You for Decades
Student loans represent one of the most significant and longest-lasting financial burdens a person can carry, and most people take them on at 18 or 19 without a realistic understanding of what repayment will look like. Interest accrues from the moment the loan is disbursed in many cases, and by the time a graduate enters the workforce, their total balance may already be higher than the amount they originally borrowed. The monthly payments then compete directly with other financial goals for the next 10 to 30 years.
The trap extends beyond the money itself. Student debt delays home ownership, delays retirement savings, delays the ability to take career risks or start businesses, and creates a persistent financial anxiety that shapes major life decisions for decades. Refinancing options, income-driven repayment plans, and employer loan assistance programs are all worth investigating thoroughly rather than simply accepting the default repayment terms that most graduates never question.
Lifestyle Inflation That Erases Every Pay Rise You Ever Get
Every time your income increases, there is a powerful, completely understandable impulse to improve your lifestyle to match it. A nicer apartment, a better car, more frequent dining out, more subscriptions, more travel. Each upgrade feels earned and reasonable, and individually, it usually is. The trap is that lifestyle inflation can expand to consume every pay rise you ever receive, leaving you earning significantly more than you did five years ago but somehow no closer to financial security.
Wealthy people consistently cite lifestyle discipline as one of the most important factors in their financial position. Not deprivation, but deliberate decisions about when and how lifestyle upgrades are appropriate relative to the underlying financial foundation they are building. The simplest, most practical approach is to commit a specific percentage of every income increase to savings or investments before adjusting any spending, and to treat that commitment as non-negotiable rather than revisiting it once you see how the new income feels.
Limited Credit Access That Traps Low-Income Families
Access to affordable credit is not evenly distributed, and the people who need it most are consistently offered the worst terms. Low-income households are more frequently denied conventional loans, are offered higher interest rates when approved, and are pushed toward high-cost alternatives such as rent-to-own arrangements and subprime lending products. The result is that the people with the least financial cushion end up paying the most to access money during difficult periods.
This creates a compounding disadvantage where the cost of being financially vulnerable makes it harder to become less financially vulnerable. Building credit deliberately through secured cards, credit builder loans, and consistent on-time payment of existing obligations is a slow process, but one that meaningfully changes the terms available over time. Community development financial institutions and non-profit credit counselors are also underused resources that offer genuinely affordable alternatives to predatory lending products.
Subscription Creep That Bleeds Your Budget Every Month
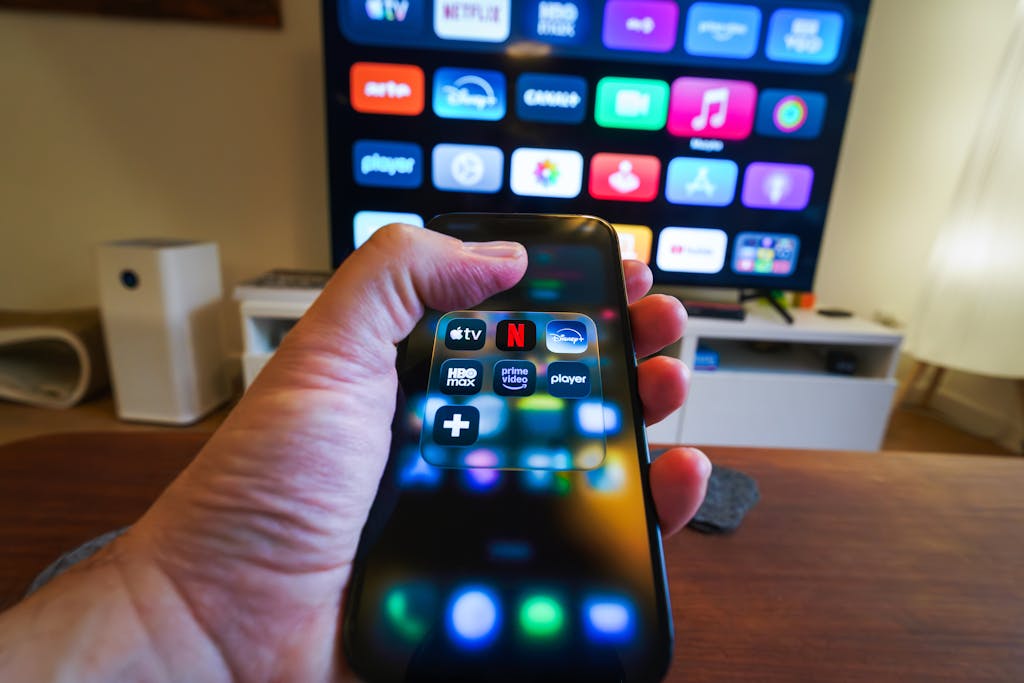
Subscriptions are designed to be easy to start and inconvenient to cancel, and most people are paying for significantly more of them than they realize or use. Streaming services, software subscriptions, gym memberships, meal kit deliveries, app purchases, cloud storage plans, and premium tiers of free services all tend to accumulate quietly over months and years until they represent a meaningful monthly drain that nobody ever consciously decided to maintain.
The financial trap is that no single subscription feels significant enough to bother canceling, but the total across all of them often amounts to hundreds of dollars per month. Conducting a full audit of every recurring charge on your bank and credit card statements every six months and canceling anything you have not actively used in the past thirty days is one of the fastest ways to recover money that has been silently leaving your account. Treating subscriptions as deliberate monthly choices rather than passive ongoing arrangements is the habit that keeps this trap from resetting.
Ignoring Retirement Savings Until It Feels Too Late
Every year that passes without contributing meaningfully to retirement savings is a year of compounding returns that cannot be recovered. The mathematics of compound interest means that money invested in your twenties and thirties does dramatically more work over time than the same money invested in your forties and fifties. Most people understand this in principle and consistently deprioritize it in practice, telling themselves they will start properly once some other financial pressure has been resolved.
The trap is that the other pressures rarely fully resolve, and meanwhile, the window of maximum compounding benefit quietly closes. Starting with whatever amount is currently possible, even a very small one, and increasing it incrementally with every income change is significantly better than waiting for the ideal moment that may never arrive. Employer-matched contributions to retirement accounts are also one of the most commonly unclaimed financial benefits available, and leaving them on the table is the equivalent of declining part of your salary.