Picture this: you’ve just won millions in the lottery. The world feels like your oyster, right? But here’s the harsh reality: winning the lottery doesn’t guarantee a happy ending. It often creates a whole new set of problems.
While the money can change your life overnight, it can also disappear just as quickly if you make these crucial mistakes. Here’s a deep dive into the mistakes that can turn your lottery win from dream to disaster and how to avoid them.
Spending the Jackpot Before You Even See It
You’ve won millions, what’s the first thing you’re going to buy? A mansion? A new car? The truth is, many lottery winners are so blinded by the initial thrill that they spend the headline number without considering what they’ll actually take home after taxes. That “$100 million” prize shrinks quickly when you factor in federal tax rates and state deductions.
The IRS takes its share, and that doesn’t even include hidden fees for lump sum payouts. So, before you start picking out paint colors for your new mansion, calculate your after-tax total. You might be surprised at what’s left after the dust settles.
Making Hasty Decisions With Emotion, Not Logic
What’s the rush? The excitement of winning can cause winners to make snap decisions, such as quitting their jobs or buying expensive gifts for friends and family. These emotional choices can backfire quickly. Before making any big decisions, take a deep breath and slow down.
Financial experts recommend waiting six to twelve months before making any life-altering changes. This cooling-off period helps prevent rash decisions driven by excitement or guilt.
Ignoring the Taxman
It’s easy to forget that the IRS will be waiting to collect its share of your prize. While the initial lump sum or annuity payout might seem like a huge sum, the reality is far less glamorous. The IRS typically takes around 24% off the top, but depending on where you live, you could end up paying even more. This means your $10 million could quickly drop to $6 million.
The lesson here? Never forget taxes; they will always take a bite out of your winnings. Work with a tax professional to ensure you’re setting aside enough to cover your bills.
Telling Too Many People Too Soon
Once the check clears, you might feel the need to shout your good news from the rooftops. But that’s exactly what you should not do. The more people who know about your windfall, the more likely it is that you’ll be bombarded with requests for loans, gifts, or even business opportunities.
Sudden wealth attracts not just well-wishers but also opportunists. Protect your privacy and set boundaries before the requests start rolling in. And remember, it’s okay to say no.
Letting ‘Everyone’ Share in Your Newfound Fortune
Nothing creates more tension than family members suddenly treating you like an ATM. Once word gets out that you’ve won, expect an influx of calls, messages, and visits from relatives and friends asking for a piece of the pie. Whether it’s a loan for a business, help with tuition, or just cash for bills, the requests never stop.
And while it’s tempting to help everyone, the reality is that giving away too much can drain your resources faster than you think. Set clear rules for financial gifting and stick to them. Your generosity should not bankrupt you.
Falling for Scams and Fake Investment Schemes
It’s not just friends and family who might try to cash in on your good fortune. Once you win, scammers are quick to find you. They may reach out with “once-in-a-lifetime investment opportunities” or offer to manage your newfound wealth with the promise of huge returns.
The reality is, the more money you have, the more predators will try to separate you from it. Protect yourself by working only with licensed professionals and ignoring unsolicited investment opportunities. If it sounds too good to be true, it probably is.
Thinking You’re Suddenly a Financial Expert
Let’s get one thing straight: Winning the lottery doesn’t make you a financial expert. Many winners fall into the trap of thinking they can easily manage their newfound wealth. However, without a solid understanding of investing, taxes, and financial planning, it’s easy to make costly mistakes.
This is where working with certified financial planners, accountants, and attorneys becomes crucial. They can help you make informed, long-term decisions that ensure your wealth lasts.
Diving Headfirst Into Risky Investments
What’s one of the fastest ways to lose a fortune? Overloading on risky investments. Some lottery winners, fueled by the belief that they’re invincible, pour their money into volatile stocks, high-risk businesses, or speculative assets like cryptocurrency. But this is where a lack of knowledge can lead to disaster.
Diversifying your investments, rather than betting it all on a single high-risk venture, is key to keeping your wealth intact. Play the long game and make thoughtful, calculated moves.
Quitting Your Job Too Soon
Many lottery winners immediately quit their jobs, thinking they no longer need to work. But leaving the workforce can come with serious emotional and psychological consequences. The structure, routine, and sense of purpose that work gives you can be hard to replace.
Slow down. Stay in your job for a while and create a plan for your post-lottery life. You may find that keeping a job offers a sense of security and keeps you grounded in the midst of your windfall.
Living Beyond Your Means
Just because you’ve won millions doesn’t mean you can live like a billionaire. Many lottery winners fall into the trap of lifestyle inflation, where their spending habits rise to match the new windfall.
Buying luxury cars, extravagant homes, and traveling around the world are all tempting options, but unchecked spending can quickly drain your savings. Plan your spending wisely, and remember that a luxurious life today doesn’t guarantee a secure future tomorrow.
Not Having an Exit Strategy
Without a long-term wealth management plan, your jackpot can quickly become a short-term mistake. This isn’t just about spending money wisely; it’s about making decisions that preserve your wealth for the future.
From creating a will to building an estate plan, long-term planning is the key to securing your financial future. Failing to do this can leave your family and wealth vulnerable to legal battles, taxes, and mismanagement.
Letting Others Manage Your Money
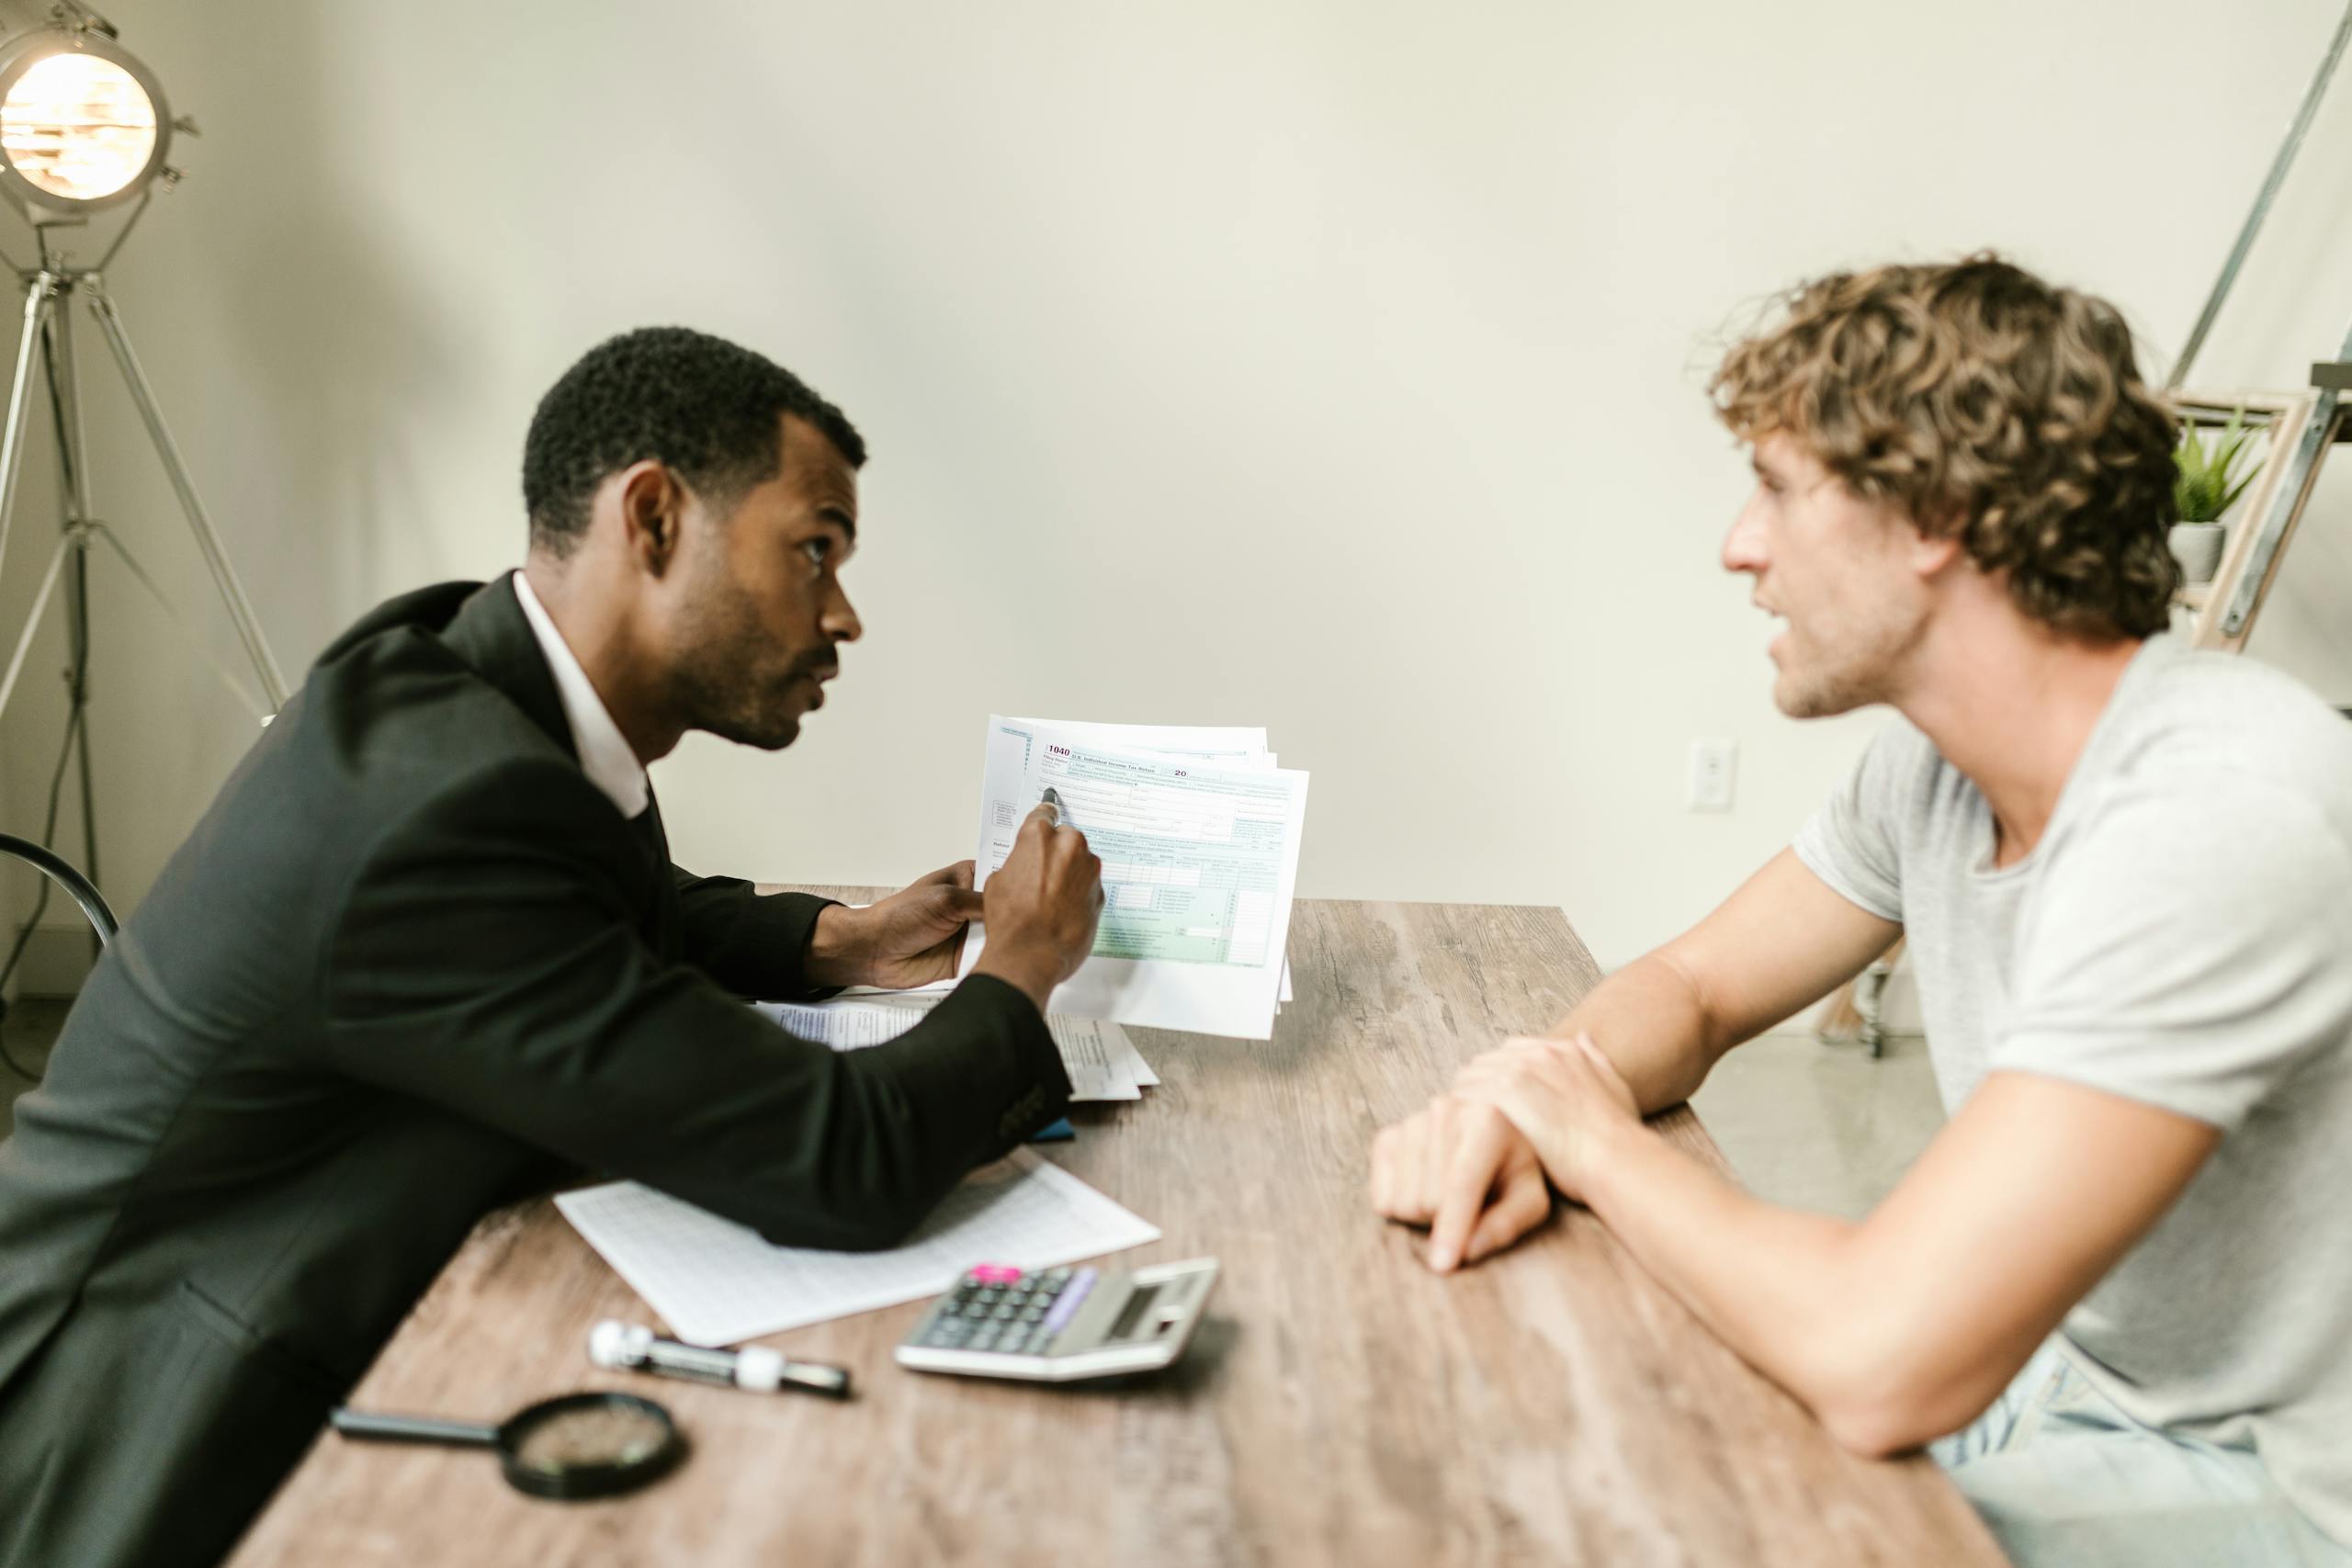
Handing over the reins of your finances to someone else can be risky. It’s common for winners to hire a financial manager or lawyer to handle everything, but they must be chosen with care.
Financial professionals with the wrong interests or who aren’t properly vetted can easily exploit your trust. Always do your due diligence and make sure your advisers are reputable and accountable.
Conclusion
Winning the lottery can change your life, but it doesn’t guarantee happiness or financial security. The mistakes listed above are all too common among winners, and they highlight how quickly newfound wealth can be lost if not managed properly.
So, if you ever find yourself in the lucky position of winning, remember: It’s not just about winning the money, it’s about winning at managing it. Take your time, hire the right experts, and build a strategy that ensures your wealth doesn’t fade away.