Many people live with an inexplicable sense of financial pressure, feeling that no matter how much they earn, their bank balance never reflects their efforts. The truth is that subtle lifestyle choices can quietly chip away at wealth, leaving individuals frustrated and wondering where the money disappears. These choices often feel ordinary, even harmless, but they add up to substantial financial leakage over time, silently eroding savings and limiting financial freedom. Understanding these habits allows us to regain control and make intentional, wealth-preserving decisions that protect both our present and future.
Impulse Purchases Driven by Online Shopping
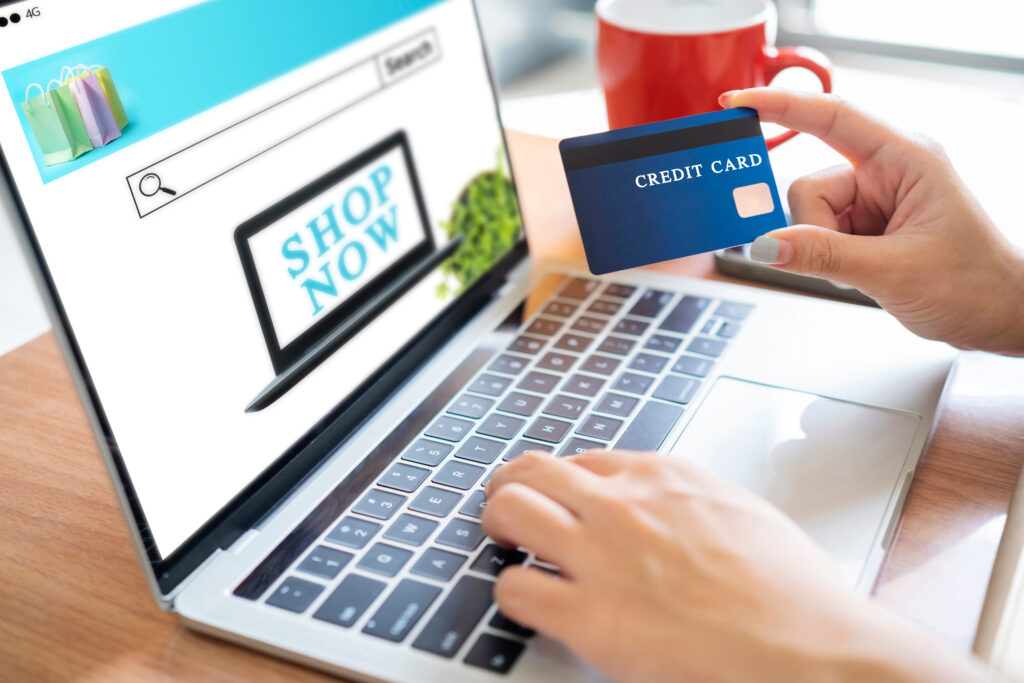
The convenience of online shopping has fostered a culture of impulse buying, in which advertisements and algorithm-driven suggestions encourage spending without deliberation. Many shoppers underestimate the cumulative effect of small, frequent purchases, which quickly drain funds without enhancing long-term value. Credit card usage exacerbates the problem by delaying the emotional impact of spending, leading to unnoticed debt accumulation.
Establishing a deliberate purchasing strategy, unsubscribing from marketing emails, and setting spending limits can prevent unnecessary losses. Awareness of the psychological triggers behind online consumption is key to halting financial leakage before it compounds.
Ignoring Subscriptions and Memberships
Automatic subscriptions to streaming services, apps, fitness programs, and magazines often remain active long after they are no longer used, quietly depleting funds. Many individuals fail to review recurring charges, allowing small monthly fees to add up to a substantial yearly expense. Conducting a thorough audit of all active subscriptions can identify redundant or unused services, freeing up money that can be redirected toward savings or investment.
This habit also reinforces conscious spending, ensuring that every expense aligns with personal value and necessity. Overlooking these charges silently undermines financial efficiency, making it one of the most pervasive money drains.
Frequent Dining Out Instead of Cooking at Home
Regularly choosing restaurants over home-prepared meals can quietly devastate a budget. The average American household spends several hundred dollars per month dining out, and this figure rises dramatically when factoring in tips and convenience fees. Meal planning, bulk grocery shopping, and learning simple recipes at home drastically reduce food costs while improving nutrition and control over ingredients.
Additionally, cooking at home transforms meals from fleeting experiences into longer-term financial and health investments. Ignoring this habit keeps individuals trapped in a cycle of expensive, often impulsive spending that silently undermines financial stability.
Overuse of Ride-Sharing Services
Frequent use of ride-sharing platforms offers convenience but comes at a steep financial cost when used habitually instead of public transit or personal transportation. Daily trips, surge pricing, and tipping add up quickly, making transportation one of the most overlooked budget drains. Strategically planning commutes, utilizing monthly transit passes, or carpooling can significantly cut expenses while maintaining mobility.
Beyond cost, reducing reliance on ride-sharing encourages a more intentional lifestyle that balances convenience with financial prudence. Failure to address this habit quietly erodes disposable income, turning convenience into a recurring drain on wealth.
Overspending on Daily Coffee and Convenience Drinks
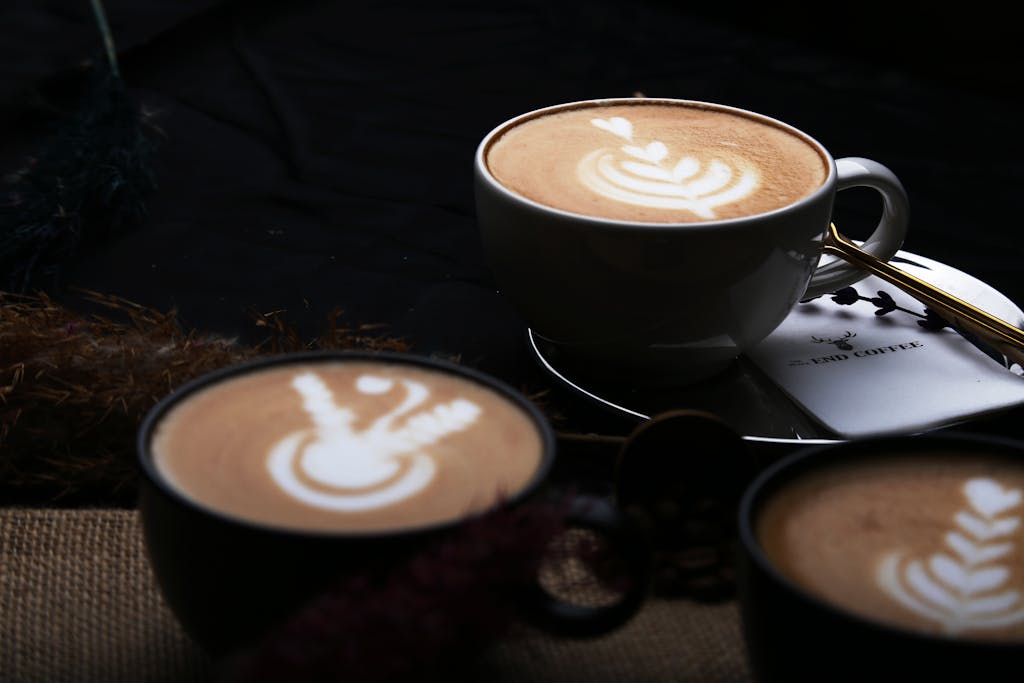
Spending a few dollars a day on coffee or specialty drinks may seem trivial, but the cumulative effect can be astonishing. Buying a $5 latte every morning adds up to hundreds of dollars per month and thousands of dollars annually, with no tangible return on investment. Beyond cost, this habit often encourages additional purchases, such as snacks or breakfast items, amplifying its financial impact.
Preparing coffee at home or limiting café visits can redirect this consistent expenditure into savings or investment accounts. Recognizing the financial ripple effect of seemingly minor indulgences is essential to reclaiming disposable income and minimizing unnecessary resource drains.
Overreliance on Credit Cards Without a Repayment Strategy
Using credit cards for convenience without a disciplined repayment strategy can create hidden financial drains. Interest rates and late fees escalate debt far beyond the initial purchase cost, quietly eroding net worth over time. Establishing a structured repayment plan, utilizing low-interest options, and reserving credit cards for planned, essential expenses prevent this compounding drain.
Monitoring credit utilization and staying within borrowing limits helps maintain financial flexibility and avoid interest accumulation. Neglecting this habit allows debt to quietly grow, undermining financial security and limiting opportunities for wealth growth.
Excessive Spending on Fashion and Trends
Keeping up with fashion trends can create a continuous cycle of spending that offers fleeting satisfaction but long-term financial consequences. Clothing and accessory purchases, particularly from high-end or fast-fashion brands, often depreciate rapidly while contributing significantly to monthly expenditures.
Mindful wardrobe management, prioritizing versatile pieces, and purchasing based on necessity rather than trend appeal prevent this drain. Budgeting for seasonal shopping and prioritizing quality over quantity ensures spending aligns with practical utility and lasting value. Allowing fashion impulses to dictate financial choices risks chronic resource depletion without meaningful gains.
Neglecting Energy Efficiency in the Home
Ignoring energy consumption habits at home leads to inflated utility bills that silently sap financial resources. Leaving lights on, inefficient heating and cooling practices, and running appliances unnecessarily increase monthly expenses without noticeable benefits. Implementing energy-efficient solutions such as LED lighting, smart thermostats, and mindful appliance use reduces costs while enhancing environmental responsibility.
Small behavioral changes, including unplugging electronics and using energy during off-peak hours, compound into substantial annual savings. Overlooking energy efficiency is a stealthy drain on funds that can be easily mitigated with simple, conscious actions.
Frequent Upgrades to Technology and Gadgets
Constantly upgrading phones, laptops, and other electronic devices imposes a subtle yet persistent financial strain. Technology purchases often depreciate quickly while creating a culture of continual consumption that discourages long-term financial planning. Evaluating the need for upgrades, leveraging warranties, and maintaining devices for longer periods ensures money is spent strategically rather than impulsively.
Prioritizing functionality over novelty prevents unnecessary financial outflow while still allowing access to essential tools. The relentless pursuit of the latest gadgets silently siphons resources, making moderation and intentionality essential for preserving wealth.
Conclusion
Many of the financial drains we encounter are invisible until they accumulate over time. By critically evaluating daily habits, spending patterns, and recurring costs, we can identify the areas silently eroding our wealth and take deliberate action to stop the leakage. Awareness and disciplined financial practices transform everyday choices into opportunities to save, invest, and build long-term security.